Bank Reconciliation Checklist for Global SMEs in 2026: The Monthly Habit That Catches Fraud Before It Compounds
US businesses lose an average of 5% of gross revenue to fraud every year, according to the Association of Certified Fraud Examiners — and small businesses are hit with the highest frequency of incidents, not the lowest, because they're the ones least likely to have a second set of eyes on the books. Bank reconciliation is the cheapest control an SME has against that number, and it's also the one most likely to get skipped when things get busy.
What Reconciliation Actually Checks
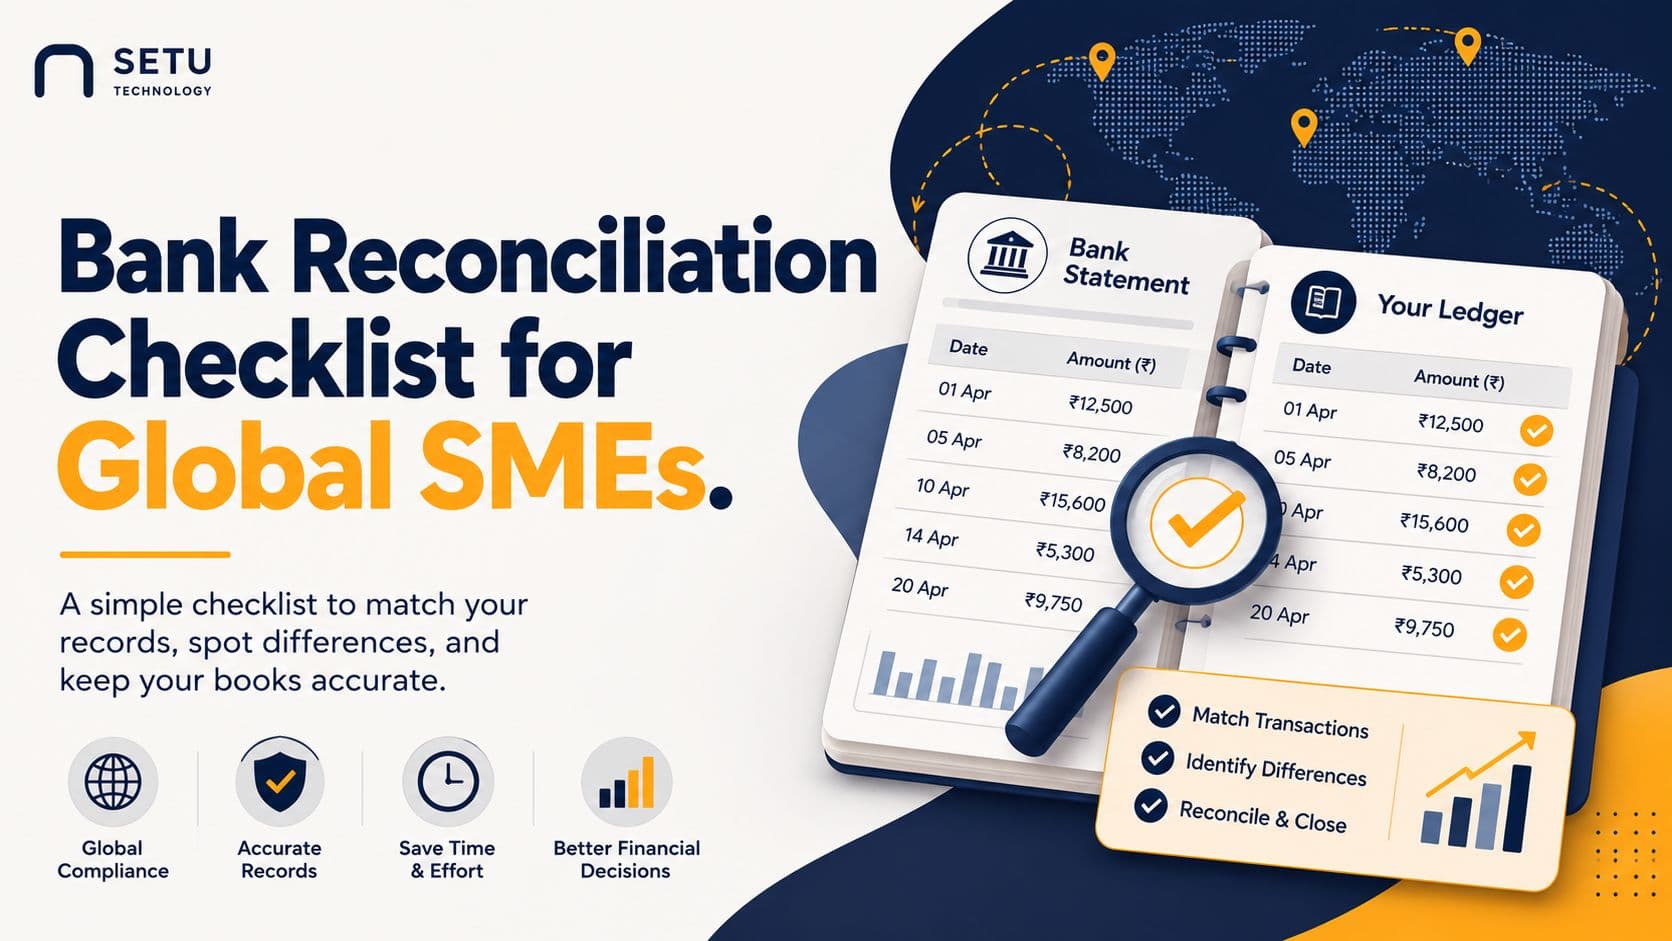
Bank reconciliation compares your accounting records against your actual bank statement, line by line, to confirm the two agree. It starts with the bank's ending balance, adds deposits in transit and subtracts outstanding checks or payments, and arrives at an adjusted bank balance. Separately, it starts with your book balance, adds any income the bank has recorded that your books haven't, subtracts any charges you haven't recorded yet, and arrives at an adjusted book balance. If the two adjusted balances don't match, something in the books or the bank feed needs explaining — not filing away.
The Checklist
- Pull the current bank statement and your internal ledger for the same period.
- Match every transaction on both sides — deposits, withdrawals, transfers, card charges.
- List deposits in transit (recorded in your books, not yet cleared by the bank).
- List outstanding checks or payments (issued but not yet cleared).
- Record bank fees, interest, and any charges the bank applied that you hadn't logged yet.
- Investigate every unmatched line individually — don't write off small discrepancies as rounding.
- Confirm no unfamiliar payees, altered amounts, or unauthorized transfers appear anywhere in the period.
- Have someone other than the preparer review and sign off before it's filed.
Why Who Does It Matters as Much as How Often
Segregation of duties is the control that actually makes reconciliation work as fraud prevention, not just error-checking. If the same person receives payments, records them, and reconciles the account, there's no independent check left in the process — an altered check amount or an unfamiliar payee can sit unnoticed for months. For a small team where one person genuinely handles everything, the fix doesn't have to be a new hire: an outsourced reconciliation review, done by someone outside the day-to-day cash handling, restores the same independence.
How Often Is Actually Often Enough
Monthly, tied to your close cycle, is the accepted minimum. But frequency should scale with risk and volume: businesses reconciling weekly or daily catch discrepancies roughly 47% faster than those waiting for month-end, because small errors get caught before they compound into a pile of unexplained transactions. For most SMEs, weekly reconciliation on the operating account and monthly on lower-activity accounts is a reasonable middle ground — the point isn't perfection, it's not letting three months of drift build up before anyone looks.
When It's Better Outsourced
Reconciliation is exactly the kind of recurring, detail-heavy task that benefits from being handled by someone whose full attention is the books, not squeezed in between running the business. Setu Technology's accounting and bookkeeping consultancy handles monthly reconciliation as a core part of the service — across QuickBooks, Xero, Zoho, and several other platforms — alongside the bank/credit card reconciliation, categorization, and monthly P&L that make the rest of your books trustworthy. Track daily cash movement yourself in the meantime with the free Cash Book and Expense Tracker tools.
Frequently asked questions
Monthly is the minimum — tied to your accounting close cycle. But if your transaction volume is high or you've had control issues before, weekly or even daily reconciliation is worth the extra time: businesses that reconcile weekly or daily catch discrepancies roughly 47% faster than those reconciling only at month-end.
More from Accounting
Setu vs BUSY Accounting Software: Free Browser Tools or a Licence in 2026?
BUSY's one-time editions are publicly listed from ₹11,000 to ₹22,000 exclusive of GST in October 2026, with a separate subscription line from ₹5,000 per 360 days. Setu's accounting tools are free browser pages. Here is where the line honestly falls.
Read more →
What to Send Your Bookkeeper Every Month, and Who Owns What
Most bookkeeping relationships stall over supply, not skill: one missing bank statement and the month cannot close. Here is the seven-part monthly pack, a task-by-task split of who owns what, and the dates worth writing into the engagement letter.
Read more →
Your Bookkeeper Sent Three Statements. Here Is How to Read Them.
Every month an outsourced bookkeeper sends a profit and loss statement, a balance sheet and a cash flow statement, and most owners glance at one number and file the rest. Here is what each statement actually answers, and in what order to read them.
Read more →
Comparing Bookkeeping Quotes: The Eight Questions That Matter
Two bookkeeping quotes use identical words and differ by three times in price, because price without scope is not a price. The eight questions that make quotes comparable, the four red flags, and an in-house cost comparison that carries its full weight.
Read more →